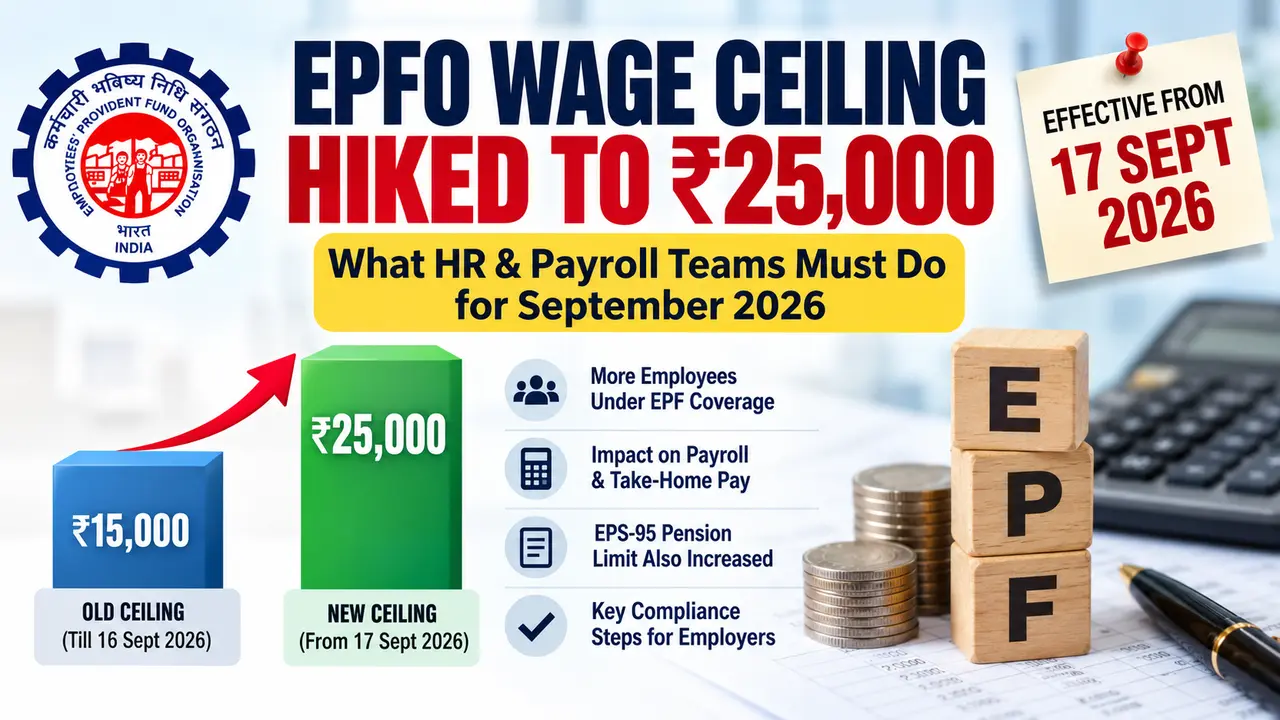
The Union Cabinet approved a major revision to the Employees’ Provident Fund (EPF) wage ceiling on September 16, 2026 — raising it from ₹15,000 to ₹25,000 per month, effective September 17, 2026. This is the first change to the ceiling since September 2014, when it was last revised from ₹6,500 to ₹15,000.
For HR and payroll professionals, this isn’t just a policy headline — it changes the statutory coverage threshold under EPF, EPS and EDLI and requires employers to review affected employees, update payroll calculations, and ensure correct reporting for the September 2026 wage month.
What Exactly Changed
The wage ceiling is the salary threshold that determines whether an employee must be covered under EPFO schemes. It is not a cap on every employee’s PF contribution — a distinction many early reports have blurred.
- Old ceiling: ₹15,000/month
- New ceiling: ₹25,000/month
- Effective date: September 17, 2026
- Expected new coverage: Over 51 lakh additional employees
- Estimated annual government outgo: ~₹11,339 crore (up from ~₹10,250 crore)
- Gazette notification: S.O. 5109(E), issued September 17, 2026 (Gazette of India Extraordinary, Part II, Section 3(ii), No. 4918)
Employees drawing wages above ₹15,000 and up to ₹25,000 who satisfy the applicable statutory conditions come within the expanded mandatory EPFO coverage. The revised ceiling applies to EPF, EPS and EDLI.
Who This Actually Affects
| Employee Situation | Impact |
|---|---|
| Employee with EPF wages above ₹15,000 and up to ₹25,000 | Comes within expanded mandatory coverage, subject to applicable statutory conditions |
| Existing EPF member whose contribution was restricted to ₹15,000 | Contribution may now be calculated on the higher applicable wage, subject to EPF/EPS provisions |
| Existing EPF member in the ₹15,000–₹25,000 range who was not an EPS member | EPS membership becomes applicable from 17 September 2026, subject to the applicable conditions |
| Employee with EPF wages above ₹25,000 | Revised statutory ceiling does not extend mandatory coverage beyond ₹25,000; applicable provisions continue |
| Employee already contributing on higher wages under an applicable higher-wage arrangement | Existing arrangement should be reviewed under the applicable EPF provisions |
New joiners after 17 September 2026
- Joining wages up to ₹25,000: covered from the date of joining. Contribution is calculated on the wages for the days worked in the month. For example, an employee joining on 21 September at ₹20,000 a month has wages of ₹6,666.67 for 21–30 September, and the employee share is ₹800.
- Joining wages above ₹25,000: generally an excluded employee, unless the employer and employee jointly opt in.
September 2026 Example: Employee with ₹20,000 EPF Wages
The contribution for September 2026 depends on the employee’s membership status.
| Scenario | 1–16 September | 17–30 September |
|---|---|---|
| A. Existing employee who becomes an EPF member from 17 September 2026 | No EPF contribution | ₹20,000 wage considered proportionately |
| B. Existing EPF & EDLI member contributing on ₹20,000, newly enrolled in EPS from 17 September 2026 | Contribution based on actual ₹20,000 wages | ₹20,000 wage considered proportionately; EPS applies from 17 September |
| C. Existing EPF, EPS & EDLI member contributing on the ₹15,000 cap until 16 September 2026, moving to ₹20,000 from 17 September 2026 | ₹15,000 ceiling applies | ₹20,000 wage considered proportionately |
For an employee with ₹20,000 monthly EPF wages, the proportionate wage for 17–30 September is:
₹20,000 × 14 ÷ 30 = ₹9,333.33
The exact September contribution depends on the employee’s membership status and the applicable scenario.
| Particulars | Scenario A | Scenario B | Scenario C |
|---|---|---|---|
| September EPF wage | ₹9,333.33 | ₹20,000.00 | ₹17,333.33 |
| September EPS wage | ₹9,333.33 | ₹9,333.33 | ₹17,333.33 |
| Employee EPF (12%) | ₹1,120.00 | ₹2,400.00 | ₹2,080.00 |
| Employer EPF (A/c 1) | ₹342.53 | ₹1,622.53 | ₹636.13 |
| Employer EPS (A/c 10) | ₹777.47 | ₹777.47 | ₹1,443.87 |
| EDLI (A/c 21 – 0.5%) | ₹46.67 | ₹100.00 | ₹86.67 |
| EPF Admin Charges (A/c 2 – 0.5%) | ₹46.67 | ₹100.00 | ₹86.67 |
| Total Statutory Remittance | ₹2,333.34 | ₹5,000.00 | ₹4,333.34 |
EPF Contribution Rates: ₹15,000 vs. ₹25,000 Wage Ceiling
At the standard 12% employee contribution rate and 12% employer contribution rate, the maximum contribution changes as follows:
- Old maximum mandatory deduction: 12% of ₹15,000 = ₹1,800
- New maximum mandatory deduction: 12% of ₹25,000 = ₹3,000
- Maximum increase in employee EPF contribution: ₹1,200/month, where the full ₹25,000 wage ceiling is applicable.
Example: An employee with applicable EPF wages of ₹20,000 who comes within the revised coverage would have an employee EPF contribution of ₹2,400 and an employer contribution of ₹2,400, with the employer share divided between EPF and EPS as applicable.
| PF Wage | Employee EPF (12%) | Employer EPS (8.33%) | Employer EPF (3.67%) | EDLI (0.5%) | Admin (0.5%) |
|---|---|---|---|---|---|
| ₹15,000 | ₹1,800 | ₹1,250 | ₹550 | ₹75 | ₹75 |
| ₹20,000 | ₹2,400 | ₹1,666 | ₹734 | ₹100 | ₹100 |
| ₹25,000 | ₹3,000 | ₹2,083 | ₹917 | ₹125 | ₹125 |
From October 2026
From the October 2026 wage month, contributions will be calculated for the full month based on the employee’s applicable EPF wages, subject to the revised statutory wage ceiling of ₹25,000.
For example, where the applicable EPF wage is ₹20,000:
- Employee EPF: ₹2,400
- Employer EPS: ₹1,666
- Employer EPF: ₹734
- Total employee + employer contribution: ₹4,800
Scenario D: Employee with ₹40,000 PF Wages (Above the ₹25,000 Ceiling)
Full-month example from October 2026 for an existing EPF, EPS and EDLI member. Only contributions up to ₹25,000 are mandatory; anything above is voluntary.
| Particulars | Mandatory (on ₹25,000) | If employer continues on ₹40,000 (voluntary) |
| Employee EPF (12%) | ₹ 3,000 | ₹ 4,800 |
| Employer EPS (8.33%, capped at ₹25,000) | ₹ 2,083 | ₹ 2,083 |
| Employer EPF | ₹ 917 | ₹ 2,717 |
| EDLI (0.5%) | ₹ 125 | ₹ 125 |
| Admin charges (0.5%) | ₹ 125 | ₹ 125 |
| Total remittance | ₹ 6,250 | ₹ 9,850 |
The additional ₹1,800 each from employee and employer on wages above ₹25,000 is voluntary and depends on the employment terms and agreement between both parties. EPS applicability depends on the employee’s membership status.
Pension Impact (EPS-95)
The revised wage ceiling also expands the scope for EPS coverage and permits pensionable wages to be considered up to the revised statutory ceiling, subject to applicable EPS provisions. However, the actual pension payable to an individual depends on pensionable salary, pensionable service and other applicable conditions.
What Employers Should Do Now
- Identify employees in the ₹15,000–₹25,000 wage band.
- Identify existing PF members whose contribution was restricted to ₹15,000.
- Identify employees who become newly covered from 17 September 2026.
- Review the statutory wage components used for PF calculation.
- Update September 2026 payroll calculations for the two applicable periods.
- Calculate contributions separately for 1–16 September and 17–30 September, as applicable.
- Ensure September 2026 contributions are correctly reported through a single ECR.
- Review EPS eligibility and membership status of affected employees.
- Review PF compliance for contract labour, wherever applicable.
- Update payroll/HR systems and employee communication.
- Maintain an audit trail of calculations and payroll changes.
- Reconcile the September ECR, challan and payroll records.
What HR Teams Need to Check
HR & Payroll Compliance Checklist
Employee Master
- Employees with PF wages ₹15,000–₹25,000
- Existing PF members restricted to ₹15,000
- Employees previously excluded from PF
- EPS membership status
Payroll
- PF wage components
- September 1–16 calculation
- September 17–30 calculation
- Employee contribution
- Employer EPF contribution
- Employer EPS contribution
- EDLI and administrative charges
ECR
- Single September 2026 ECR
- Correct period-wise calculation
- EPF/EPS membership and enrolment
- ECR vs payroll reconciliation
Documentation
- Payroll calculation working
- Wage/membership assessment working
- Employee communication
- UAN/KYC status
- ECR
- Challan
- Payment proof
- Audit trail
Reference Documents (PDF copies)
Copies provided for reference. Always confirm the latest version on the EPFO portal (epfindia.gov.in).
EPFO Wage Ceiling Notification S.O. 5109(E)
EPFO Circular on Wage Ceiling Revision (PDF copy)
FAQs on EPFO Wage Ceiling Revision (PDF copy)
Frequently Asked Questions
Is PF calculated on ₹25,000 for September 2026?
The revised ₹25,000 wage ceiling is effective from 17 September 2026. Therefore, September 2026 contribution calculations should take into account the two periods: 1–16 September under the earlier ₹15,000 ceiling and 17–30 September under the revised ₹25,000 ceiling, as applicable to the employee. Employers are required to report September 2026 through a single ECR, with the appropriate contribution calculation for the two periods.
Does this mean every employee’s PF is now calculated on ₹25,000?
No. ₹25,000 is the revised statutory wage ceiling for mandatory coverage. The actual PF contribution depends on the employee’s applicable PF wages and statutory conditions. Employees earning below ₹25,000 are not automatically calculated on ₹25,000.
When will payroll systems be updated?
Employers should update their payroll systems to reflect the revised ₹25,000 wage ceiling effective from 17 September 2026. For September 2026, payroll calculations should account for the two applicable periods: 1–16 September under the ₹15,000 ceiling and 17–30 September under the revised ₹25,000 ceiling, as applicable. The September wage month is to be reported through a single ECR, with the applicable contributions correctly reflected. Employers should also ensure that their payroll, ECR and reconciliation processes are aligned before the 15 October 2026 filing deadline.
Is a separate ECR required for September 2026?
No. Employers do not need to file two ECRs. September 2026 should be reported through a single ECR, taking into account the two applicable wage-ceiling periods.
What if the additional PF deduction could not be recovered from September salary?
The employee share may be recovered from the subsequent payroll cycle for take-home salary adjustment, without prior approval from the Inspector-Facilitator. However, the full statutory contribution must still be reported and remitted through the September ECR within the prescribed timeline.
Will employees between ₹15,000 and ₹25,000 automatically become EPS members?
Employees newly brought within the revised coverage are subject to EPS membership under the applicable statutory conditions. Existing EPF members in the ₹15,000–₹25,000 range who were previously excluded from EPS may need to be enrolled in EPS from 17 September 2026.
Does gross salary determine PF coverage?
No. Gross salary and PF wages are not necessarily the same. PF coverage and contribution are determined with reference to the applicable statutory wage definition and EPF provisions.
Find More Related Posts :